

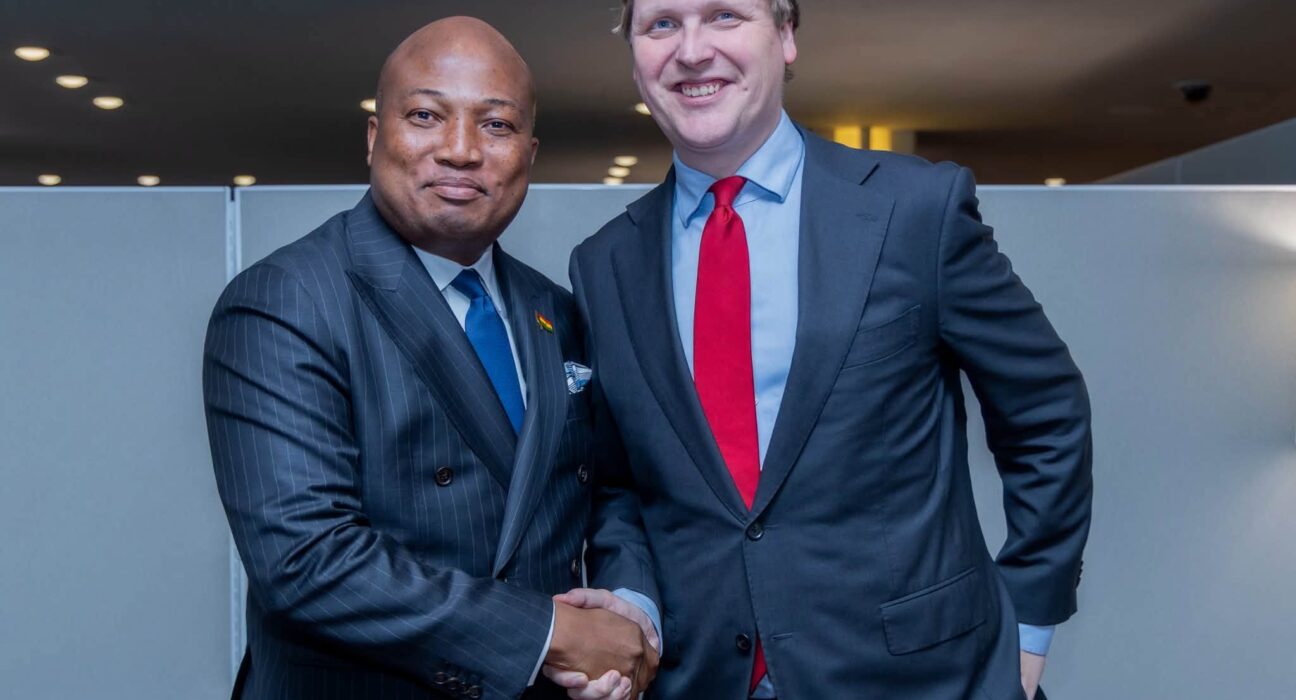
Ghana’s Minister for Foreign Affairs, Samuel Okudzeto Ablakwa, and Norway’s Minister of International Development, Åsmund Grøver Aukrust, have discussed steps towards implementing the Ghana–Norway Double Taxation Agreement as the two countries seek to deepen economic cooperation.
The discussion took place on the margins of the 81st United Nations General Assembly in New York, where the two ministers also discussed trade, investment and regional security.
The Double Taxation Agreement was signed in Accra on November 20, 2020, but has not yet entered into force. Under the agreement, Ghana and Norway are required to notify each other through diplomatic channels once they have completed the domestic procedures necessary for the treaty to take effect. It will enter into force on the date of the later notification.
The treaty is designed to establish rules for taxing income arising across the two countries and to prevent taxpayers from being exposed to taxation on the same income in both jurisdictions. It applies to residents of Ghana, Norway or both countries and covers taxes on income, including Ghana’s income tax and specified Norwegian income taxes.
Importantly, the agreement does not mean that income earned across the two countries becomes automatically tax-free. Rather, it determines when income may be taxed in Ghana, when it may be taxed in Norway, and how tax paid in one country should be treated when the same income is also subject to tax in the other.
Under the agreement’s rules on business profits, profits of an enterprise from one country would generally be taxable only in that country unless the enterprise carries on business in the other country through a permanent establishment there.
Where such a permanent establishment exists, the other country may tax the portion of the profits attributable to that establishment. The treaty defines permanent establishments to include places such as offices, factories, workshops, mines and oil or gas wells, with specific rules also applying to construction projects and certain services.
The agreement also establishes rules for cross-border payments such as dividends, interest and royalties. For dividends, the treaty limits withholding tax in the source country to 7% where a qualifying company holds at least 10% of the paying company for the required period, and 15% in other cases.
Interest is generally subject to a maximum 7% withholding tax in the country where it arises, while royalties are subject to a maximum 10% rate under the treaty, subject to the conditions set out in the respective provisions.
The agreement further provides mechanisms for eliminating double taxation. In Ghana, tax paid in Norway on qualifying profits, income or capital gains may be credited against Ghanaian tax on the same income, subject to the treaty’s conditions and limitations. Similarly, Norway is required to provide relief for qualifying income taxed in Ghana, in accordance with the agreement.
At their New York meeting, Ablakwa and Aukrust also discussed expanding trade and investment cooperation, particularly in oil and gas, renewable energy, artificial intelligence and agribusiness. The discussions further covered maritime security, education, skills development and stronger business-to-business engagement between Ghana and Norway.
The two ministers also exchanged views on security developments in West Africa, including Ghana’s efforts to strengthen regional cooperation against terrorism and violent extremism amid the growing security challenges emanating from the Sahel.
The engagement ended with an invitation for Minister Ablakwa to undertake an official visit to Oslo later this year. Ablakwa said the two countries remained committed to strengthening their bilateral and multilateral relationship.
Related Posts